Do you actually know what's happening with your workplace pension?
I retired at 50 with 33 years of contributions banked. I wasn't on a big salary and I wasn't particularly clever about it. I just paid attention.
My school leaving report in 1979 was not, let's say, effusive.
"At some point David will have to apply himself. He can't expect to survive on native wit alone."
Seemed a bit harsh at the time. Probably not too wide of the mark, mind. I left with O levels in Spanish, French and English, none of which felt especially useful as I talked my way into a job at British Rail, working in their engineering drawing office. I couldn't draw to save my life. Fortunately, all they wanted me to do was fold the paper plans that other, more skilled people had created.
Six months of mind-numbing origami. Then another twenty years of a wide variety of jobs, moving gradually upwards, sideways, occasionally backwards, until I became the media relations manager for the London–Edinburgh intercity train service. The Spanish and French turned out to be largely irrelevant. The native wit, as it happened, was essential.
Daily sparring with journalists, radio presenters and TV crews. Explaining away any number of rail industry failings. Finding the good stories, and there were good stories, to promote train travel. I later became what I privately called the "can you go" communications manager. Not my actual title, but an accurate description: the person the business turned to when they needed someone to talk to local councils, transport groups or MPs at short notice.
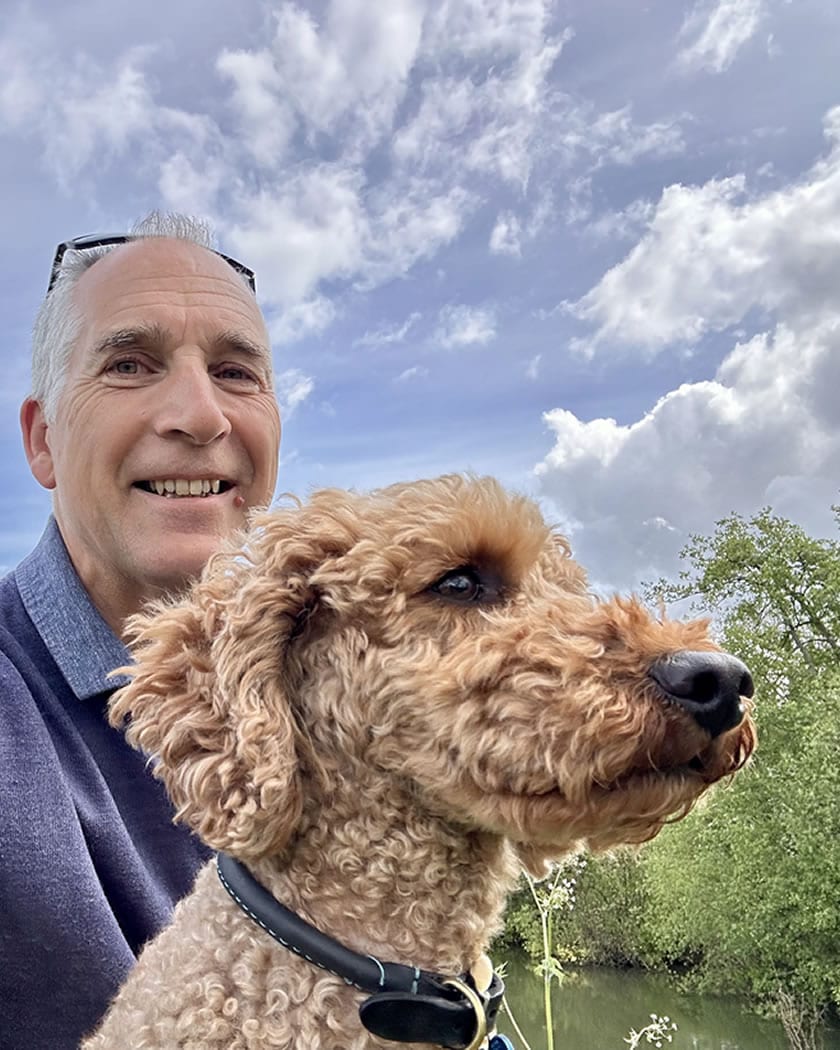
"In 2012, I retired at the age of 50 with 33 years of contributions to the pension fund safely banked."
Not a director. Not on a megabucks salary. Just a regular bloke who paid attention.Which brings me to the point of this piece. Because the pension didn't happen by accident. And it didn't require a financial advisor, a complicated investment strategy, or any particular brilliance. What it required was something far simpler: I actually read the paperwork.
Why most people don't engage with their pension
I understand it, genuinely. Pension statements are designed by people who have apparently never considered that the reader might have a life to be getting on with. They're dense, jargon-heavy, and seem specifically engineered to make your eyes slide off the page before you've taken anything in.
Add to that the fact that retirement feels abstract when you're in your thirties and forties, something that will be sorted out eventually, by some future version of you who has more time and more understanding of what "defined benefit" actually means, and it's not surprising that most workplace pensions are something people contribute to without thinking much about.
That's a mistake. And I say that as someone who made plenty of mistakes, just not this particular one.
What I actually did
Nothing exotic. Every year, when my pension statement arrived, I read it. When I didn't understand something, I either looked it up or picked up the phone to the pensions team, who, in my experience, were almost always helpful, because most of their members never called.
I kept track of my projected retirement income at different ages. I understood how the scheme worked, in my case a final salary (defined benefit) scheme, which is increasingly rare now but worth understanding if you're lucky enough to still be in one. And I made sure that my contributions were actually being made, at the right rate, and that my employer was matching them correctly.
That last one sounds obvious. It's less obvious than you'd think.
Worth knowing: Errors in pension contribution records do happen, employer contributions occasionally not paid, salary changes not reflected, periods of leave miscalculated. They're rarely deliberate, but they compound over time. The only way to catch them is to check.
The questions worth asking about your workplace pension
Whatever kind of pension you have, defined benefit (final salary), defined contribution (money purchase), or a newer workplace auto-enrolment scheme, there are some fundamental things worth understanding. Here's where I'd start.
What type of pension do you have?
This matters more than most people realise. A defined benefit scheme promises a specific income in retirement, usually based on your salary and years of service. A defined contribution scheme, which is what most people enrolled since roughly 2000 will have, builds up a pot of money that's invested on your behalf, and what you get out depends on how much went in and how those investments performed. These are very different animals, and the questions you ask are different for each.
What's your projected pension income?
Your annual statement should include a projection. Read it. Understand what assumptions it's based on. Ask what happens to that figure if you retire five years earlier or later than the assumed age. For defined contribution schemes, ask what the projected pot size translates to as an annual income, the figure shown is often just the pot value, which requires a separate conversation about drawdown or annuity rates.
Is your employer paying what they should be?
Since 2019, auto-enrolment rules in the UK require a minimum total contribution of 8% of qualifying earnings, at least 3% from your employer, at least 5% from you. Many employers pay more. Some pay significantly more if you increase your own contributions. Check your payslips. Check your pension statements. Make sure the numbers tally.
How is your pot invested?
For defined contribution schemes, your money is invested, and if you've never chosen otherwise, it's almost certainly sitting in your scheme's "default fund." That default isn't necessarily bad, but it's worth understanding what it is, how it's performing relative to other options, and whether it's appropriate for your age and planned retirement date. Most schemes offer a range of funds. Most members never look at them.
What are the charges?
Charges on defined contribution pensions vary. Auto-enrolment schemes are capped at 0.75% annual management charge for default funds, but charges across the wider range of investments can be higher. Over thirty years, the difference between 0.3% and 1% in annual charges is enormous. We're talking tens of thousands of pounds on a typical pot. It's worth knowing what you're paying.
Do you have old pensions from previous employers?
The average person in the UK now has eleven different jobs over their career. That's potentially eleven different pension pots. Finding them, understanding them, and deciding whether to consolidate them (carefully, with proper advice) is genuinely worthwhile. The government's Pension Tracing Service is free and can help locate schemes you've lost track of.
A simple starting checklist
- Find your most recent pension statement and actually read it
- Identify whether you have a defined benefit or defined contribution scheme (or both)
- Check that your employer contributions appear on your payslips at the correct rate
- Find out what fund(s) your defined contribution pension is invested in
- Note your projected retirement income and the assumptions behind it
- List any previous employer pensions, and track them down if you've lost contact
- Check whether increasing your contributions would trigger higher employer matching
- Note when you can access your pension and what options you'll have at that point
The native wit, revisited
I think about that school report sometimes. The teacher wasn't wrong, but what they perhaps didn't account for is that native wit, applied consistently in the right places, does a perfectly reasonable job.
You don't need to become a pension expert. You don't need a financial advisor (though for complex situations, a fee-only one can be worth every penny). You need to spend perhaps two hours a year reading your statement, asking a few questions, and making sure things are roughly as they should be.
Thirty-three years of doing that got me to retirement at fifty. Not because I was clever. Because I turned up and paid attention.
Useful resources
MoneyHelper (moneyhelper.org.uk), the government-backed financial guidance service. Free, impartial, and genuinely useful for pension questions at any stage.
The Pension Tracing Service, gov.uk/find-pension-contact-details, helps you track down lost workplace pensions. Free.
The Pensions Advisory Service, part of MoneyHelper. Free guidance from pension specialists, available by phone or online.